Save Your Retirement With Companies Like P&G
Key Takeaways
Strong dividend-paying companies can provide more retirement income than low-yield investments alone.
Dividend growth can continue to build income even when stock prices remain flat.
A diversified basket of quality dividend growers can potentially improve retirement security and reduce the risk of running out of money.
More than half of those approaching retirement fear that they will run out of money. Because of this we have a record number of people in this country working into their 70s. There are also more people than ever before that have cut their expenses to the bone, moved in with their children, or have sold their home and moved into a low-cost apartment just so they are sure they won’t run out of money.
Needless to say, this isn’t the dream retirement that so many people had. Not only is this a tough state of affairs to be in, but the whole situation was likely entirely preventable for many of them.
A large part of the problem for many of those approaching retirement is that they either a) Invested way too heavily in low-yielding treasuries or money markets or b) They had most or all of their money in stocks during the crash of 2008/2009 and then pulled their money out near the lows.
This article is not going to recommend that people invest heavily in stock funds or ETFs for the rest of their lives. This strategy has gotten too many people into way too much trouble over the past 15 years. What I want to discuss today is how carefully selecting and investing in strong dividend paying stocks, such as Procter & Gamble (PG), can pay off big time in the long-run and reduce stress immensely as movements in the stock price eventually barely matter.
Although I will focus on Procter & Gamble in this discussion, the strategy here applies to many companies that have a solid history of increasing (or at least not cutting) their dividends over time, even during recessions. Other companies that fit this mold are Johnson & Johnson (JNJ), Coca-Cola (KO), Exxon (XOM), and Wal-Mart (WMT).
Let’s take a look at what makes companies such as Procter & Gamble such a solid investment for retirement portfolios.
Not only does P&G have a strong dividend yield of 3.2%, but their dividend has been growing at a solid rate of 12% over the past five years. Their payout ratio is relatively low at 58%, which leaves even more room to grow their dividend over time. And perhaps the most amazing statistic is their dividend growth rate during the painful recession of 2008-2009. Even in this environment they were able to grow their dividend by 25%.
What I want to show today is how a dividend paying stock like P&G can change a person’s entire retirement situation. I want to take a look at a 45 year old couple that has been scared out of the stock market and currently has everything invested in long-term treasury bonds at 2.8%. They currently have $400,000 saved. Let’s also apply an inflation rate of 2% for each year. They plan on retiring when they are 65. How much money can they expect to have when they retire if we take into account inflation? For this example I assumed half of their money was in a qualified, non-taxable account such as an IRA. They pay taxes at a 30% rate on their investment income and dividends are taxed at a 15% rate.
Here are the results for this couple if they keep all of their money invested in low-yielding treasuries:
In 20 years their investments have only grown by a mere $45,890 if we reduce everything by the inflation rate. That is only 0.57% per year in real terms. I plugged in these numbers into our Retirement Planner and found that this couple would only have a 15% chance of not running out of money if they save $10,000 a year for the next 20 years, spend $45,000 a year in retirement and receive $35,000 a year in social security payments. This couple is headed for serious trouble.
Now let’s look at the case where they invest in a basket of solid dividend payers such as P&G. It is important to note that I am not recommending investing in just one stock. I am recommending investing in a basket of solid dividend paying stocks that have characteristics similar to P&G.
In this example I assumed a dividend yield of 3.2%, long-term dividend growth of 8%, and no increase in the stock price at all. I ran these numbers in our free online calculator called Dividend Yield And Growth.
Now we’re talking some real money when they retire. They will have almost $800,000 (in today’s dollar terms) when they retire. Plugging these numbers into our Retirement Planner I found that they now have a 70% chance of never running out of money in retirement. It is important to keep in mind that I assumed no change in the stock price in this example. I wanted to show how just collecting the dividends from strong dividend growth stocks can have such a large impact.
Because of the time factor involved with dividend growth stocks it is of utmost importance to begin investing wisely when you’re relatively young. For those who are already in their 60s this strategy will not be as useful, although it can still be a significant part of their overall strategy.
WealthTrace can run your portfolio through a bear market and show you how it could affect your retirement plans. Learn more.
In a short period of time, let’s say the portfolio loses 30% of its value. Living expenses, meanwhile, definitely do not go down by 30% over the same period. That initial 2% drawdown rate now jumps to more like 3% at exactly the wrong time. They’ll be pulling out money faster and faster just as the market has taken a big bite out of the account.
Pension To The Rescue
It can be a different story, however, if one or both of the plan participants have a pension.
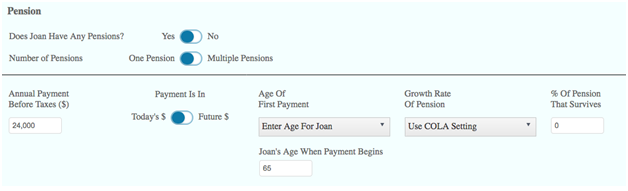
Pensions are less common than they used to be, but can make a big difference during the lean years of a retirement plan.
In this example, one person in the couple is projected to have $24,000 coming in via a pension--about what the couple would need to cover that 2% portfolio drawdown. Instead of pulling out portfolio principal when the market corrects, they can rely on the income from the pension.
Things To Consider With A Pension
WealthTrace can help you drill down into a retirement plan that accounts for pension income. You’ll want to know a few things before you get started inputting the information:
When does the payout start? Similar to Social Security, you might have some say about this (and the sooner you start to take the payments, the less it will be each year).
How much will the payout be to start with? See previous item--one likely depends on the other.
At what rate will the pension benefit grow (if it grows at all)? Sometimes pensions are indexed to inflation, sometimes not.
How much, if any, of the pension will continue to be paid out to the surviving spouse? Most likely, at least some portion of it will be paid out--the survivor’s benefit--in the event that the pensioner dies before his or her spouse does.
Is there a chance the pension will be reduced, or even disappear? This is a tricky one, and painful to contemplate. But industry landscapes change; pension funding projections can be too optimistic; the future is unknowable. It might make sense to trim back projected pension benefits a bit just to be conservative when putting your plan together.
Most retirees will take cash flows any way they can get them, but pensions are among the best ways. Count yourself fortunate if you have one--and make sure to account for it properly when putting your retirement plan together.
There is a lot more to a successful retirement plan than just hitting a number. You’ll want to WealthTrace covers all the bases. Learn more.
Find out if your income can support retirement
WealthTrace connects investment income, savings, spending, and retirement longevity.